L&T Technology Services Secures $203 Million in Deals as AI-Led Growth Drives Q2 FY27 Performance


5 Sources
[1]
LTTS Secures $203 Million in Large Deals, More Than Half AI-Led
L&T Technology Services reported $120 million in annualised Engineering Intelligence revenue as EBIT margins rose to 16.3% in Q2 FY27. In Q2 FY27, L&T Technology Services (LTTS) reported $317.1 million in revenue, up 4.8% year-over-year in constant currency. This performance was driven by $203
[2]
Why L&T Technology shares jumped 11% to hit the Rs 4,000 level afterQ2 results
L&T Technology Services shares rose sharply past Rs 4,000 after Q2 results beat expectations, driven by margin expansion, AI-led deal wins and strong sustainability business growth. Management expects a stronger second half of FY27, while Motilal Oswal, Nuvama and Nomura raised their target prices
[3]
L&T Technology Services Reports 12.1% YoY Revenue Growth and 66.8% Net Profit Growth in Q2FY27
Annualized revenue from EI-led Solutions at $120 Mn in Q2FY27 L&T Technology Services Limited aannounced its results for the second quarter ended September 30, 2026. Highlights for Q2FY27 include: * Revenue at ₹30,404 million; growth of 3.4% QoQ and 12.1% YoY * USD Revenue at $317 million;
[4]
L&T Tech Q2 FY27 slides: margin expansion accelerates, AI revenue grows By Investing.com
L&T Technology Services Limited (NSE:LTTS) presented its second quarter fiscal 2027 results on October 19, 2026, in Mumbai, showcasing margin expansion that exceeded internal targets while navigating mixed segment performance. The engineering services provider reported EBIT margins of 16.3%,
[5]
Earnings call transcript: L&T Technology Services posts solid Q2 2026 results By Investing.com
L&T Technology Services reported a solid second quarter for fiscal 2027, with revenue of INR 3,040 crores, or $317.1 million, and EPS from continuing operations of INR 35.78, slightly above the INR 35.21 forecast. The company also said EBIT margin rose to 16.3%, while the stock fell 2.78% to
Share
Copy Link
L&T Technology Services secured $203 million in large deal wins with over 50% driven by AI-led initiatives in Q2 FY27. The company reported $120 million in annualized AI revenue and EBIT margins of 16.3%, reaching its mid-16% target ahead of schedule while launching an Engineering Intelligence Lab with NVIDIA.
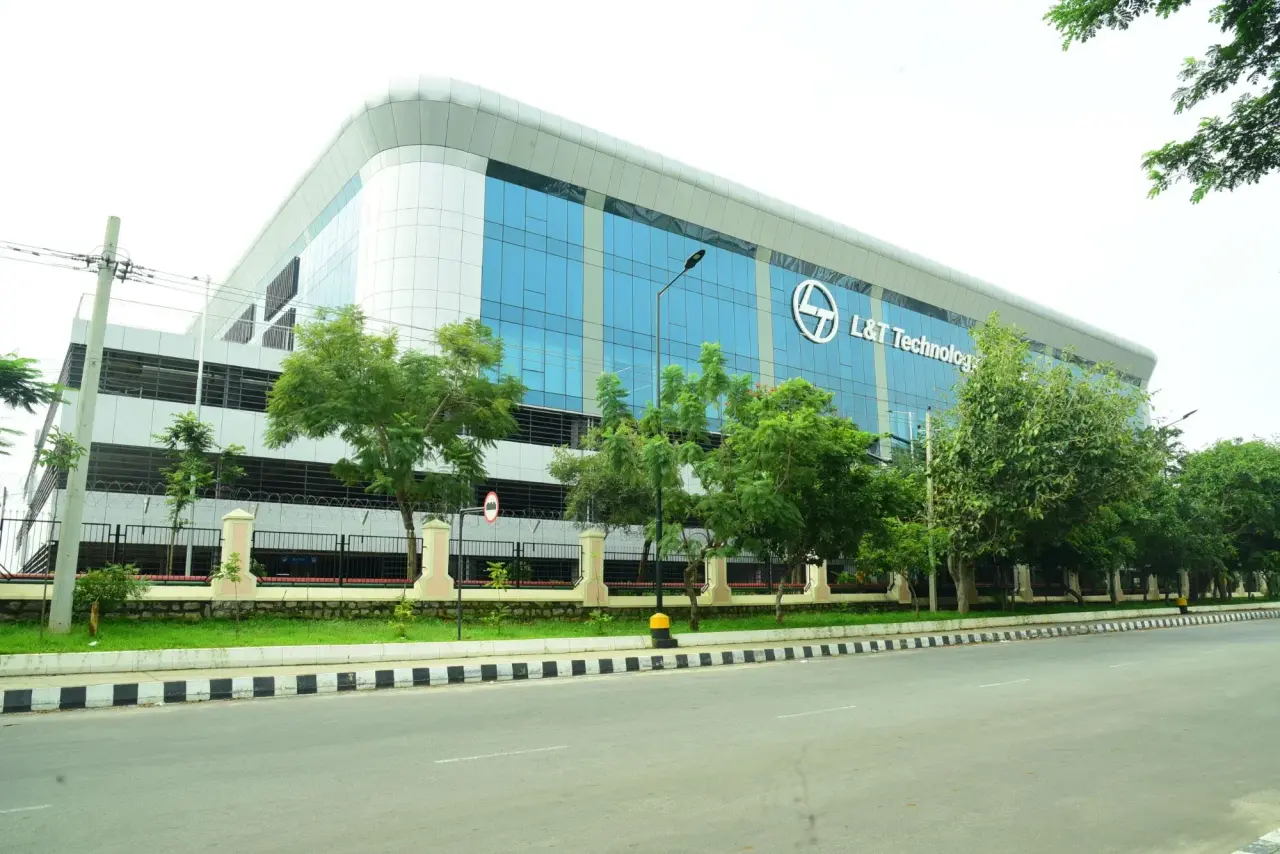
L&T Technology Services delivered a robust Q2 FY27 results, demonstrating how AI-led growth is reshaping the engineering services landscape. The company secured $203 million in large deal wins, with over 50% powered by AI-driven solutions, signaling a fundamental shift in how clients are allocating technology budgets
1
2
. This performance matters because it provides concrete evidence that AI investments are converting into measurable revenue streams rather than remaining experimental pilot projects.Revenue Growth and Margin Expansion Beat Expectations
L&T Technology Services reported revenue of $317.1 million in Q2 FY27, representing 4.8% year-over-year growth in constant currency terms and 2.7% sequential growth
3
. In rupee terms, revenue reached ₹3,040 crore, up 12.1% year-over-year and 3.4% sequentially. The company's EBIT margin expansion to 16.3% marked a 60 basis point sequential improvement and 220 basis point year-over-year gain, achieving its mid-16% target two quarters ahead of schedule4
. Net income surged 66.8% year-over-year to ₹548.2 crore, though this included a one-time gain of ₹165 crore from the sale of its Smart World and Communication business. Excluding this gain, adjusted profit after tax rose 19.7% year-over-year to ₹380 crore2
. The margin performance exceeded analyst expectations, with Motilal Oswal and Nomura both forecasting 15.6% EBIT margins.AI Revenue Reaches $120 Million Annualized Run Rate
The company's Engineering Intelligence initiatives generated $120 million in annualized revenue, representing approximately 9.5% of quarterly revenue
1
5
. This marks a critical inflection point where AI transitions from a technology theme to a commercial driver. More than 16,000 engineers, equivalent to 67% of the workforce, have been trained in AI capabilities2
. The company's EIOne platform now includes over 100 solutions spanning engineering, products, manufacturing, and operations. CEO Amit Chadha emphasized that large deal wins from earlier quarters are converting into revenue while the pipeline remains robust. Watch for whether this AI revenue percentage continues expanding in coming quarters, as it will determine if L&T Technology Services can sustain premium valuations relative to peers.Strategic Partnerships Accelerate Physical AI Development
L&T Technology Services launched an Engineering Intelligence Lab with NVIDIA to develop Physical AI applications for manufacturing, robotics, and supply chains
1
3
. The company also expanded partnerships with Anthropic, Databricks, and leading hyperscalers to strengthen its AI ecosystem. Industrial AI applications are demonstrating dramatic productivity improvements, with Shodh AI reducing a factory optimization task from 500 hours to 5.6 hours1
. The NVIDIA partnership positions L&T Technology Services to capitalize on the emerging Physical AI market, where AI systems interact with the physical world through robotics and automation. An AI-led engagement with a global telecom equipment provider to design systems for AI data centers began ramping up during the quarter1
, indicating clients are moving beyond experimentation to large-scale implementations.Patent Portfolio and Innovation Leadership
L&T Technology Services reported more than 250 AI patent filings during Q2 FY27, bringing its total patent portfolio to 1,808, including 1,085 co-authored with clients
1
2
. Management believes the company is nine to 12 months ahead of peers in Engineering Intelligence capabilities2
. This intellectual property position matters because it creates barriers to entry and demonstrates deep technical capabilities that clients value when selecting partners for mission-critical AI implementations. The high percentage of client co-authored patents suggests strong collaborative relationships that typically translate into longer-term engagements and higher switching costs.Large Deal Momentum and Pipeline Expansion
The company secured one $75 million deal, one deal exceeding $30 million, one $25 million deal, and six deals worth more than $10 million each during the quarter
1
3
. Management is targeting a quarterly large-deal run rate of approximately $200 million, with the pipeline rising more than 25% year-over-year2
5
. Nearly half of the large deal wins were linked to the sustainability business, which grew 13.4% year-over-year and 2.9% sequentially1
. The sustainability segment now accounts for 38% of revenue and maintains the highest EBIT margin at approximately 29.5%2
4
. Technology spending is shifting toward AI infrastructure, silicon, cloud platforms, and data centers, creating tailwinds for L&T Technology Services' positioning.Related Stories

Segment Performance Shows Mixed Results
The mobility segment delivered 2.3% sequential growth, supported by North American automotive, aerospace, rail, and trucks businesses
1
4
. However, European automotive remained weak amid original equipment manufacturer restructuring, with recovery expected over the next nine to 12 months2
. The technology segment declined 0.9% sequentially, affected by a MedTech program ramp-down and delayed follow-on work, though tech infrastructure and semiconductors performed strongly2
. Management expects technology growth to remain muted in Q3 with recovery from Q4. Gross margins improved across all business segments despite the mixed top-line performance3
.Market Reaction and Analyst Perspectives
Despite strong results, L&T Technology Services shares declined 2.78% to $3,611.30 following the announcement, suggesting investor caution about near-term headwinds
4
5
. Motilal Oswal retained its Neutral rating while raising its target price to ₹3,850 from ₹3,400, noting that the engineering research and development industry would take more time to recover from weak macroeconomic conditions2
. Nomura maintained a Neutral rating and raised its target price to ₹3,500 from ₹3,290. The gap between the stock's rally and brokerage target prices underscores the market's willingness to price in faster conversion of AI-led deal wins into revenue. Investors appear focused on management's comments that Q3 could be muted in some business areas and that wage hikes will pressure margins by 50 to 80 basis points5
.Future Outlook and Strategic Positioning
Management expects revenue momentum to strengthen in the second half of FY27 as large deals ramp up and earlier wins convert into revenue
1
5
. CEO Amit Chadha reiterated the company's aspiration to achieve revenue CAGR of 13% to 15% and EBIT margins of 16% to 17% over the next five years1
. The margin target will be tested by wage hikes scheduled for Q3, but management expects to maintain margins at mid-16% levels through favorable business mix, AI-led productivity gains, and disciplined selling, general and administrative expenses2
. Free cash flow for the first half reached ₹789.6 crore, representing 108% conversion of net income4
5
. The critical question for investors is whether AI-driven productivity gains will translate into sustained revenue growth and margin expansion as clients seek lower delivery costs, an issue shaping expectations across the Indian IT sector.References
Summarized by

Navi
[3]
[4]
Related Stories
L&T Technology Services Reports Strong Q1 FY26 Growth, Launches AI Framework PLxAI
17 Jul 2025•Business and Economy

L&T Technology Services Acquires Intelliswift for $110 Million to Boost AI and Digital Engineering Capabilities
11 Nov 2024•Business and Economy

LTIMindtree Reports Strong Q4 and FY25 Results, Driven by AI-Led Deal Wins
23 Apr 2025•Business and Economy

Recent Highlights



Recent Highlights
Today's Top Stories






Don’t drown in AI news. We cut through the noise - filtering, ranking and summarizing the most important AI news, breakthroughs and research daily. Follow topics that matter to you and stay ahead.


