Nebius shares slide as data centre delays push revenue into 2027


2 Sources
[1]
Nebius: 'Delays are part of our industry right now. We are not immune'
Revenue rose to $980.8m and beat estimates, but delayed third-party sites push some sales into 2027. Nebius now plans to spend up to $45bn next year. Nebius shares fell 16% on Thursday after the Amsterdam-based AI cloud company cut its outlook for this year. It also raised its spending plans,
[2]
Nebius Lowers Fiscal Year Outlook, Addresses Worries Over Financing AI Buildout
Nebius Group lowered its full-year revenue outlook, citing a delay in some third-party capacity. The artificial-intelligence cloud company also addressed recent concerns over financing its buildout, emphasizing its momentum with customer prepayments. Nebius said Thursday it now expects full-year
Share
Copy Link
Nebius cut its 2026 revenue outlook because third-party data centre capacity will arrive late. Shares fell sharply even as the company reported a 571% revenue surge and bigger spending plans.
Nebius cut its 2026 revenue outlook on Thursday because data centre capacity it was counting on will arrive late; its shares fell sharply the same day
2
1
.The strange part is what came with the cut. The Amsterdam-based AI cloud company, which rents and builds computing capacity for customers like Microsoft and Meta, also reported quarterly revenue of $980.8m, up 571% year on year
2
1
. That beat estimates near $907m2
1
. One report put the premarket share fall at 12%, another the session decline at 16%; they may measure different points in the day2
1
.A late third party
By the company's account, the cut is a timing shift. Guidance now sits at the low end of the prior $3bn-$3.4bn range
2
1
. Third-party capacity Nebius expected online this year has slipped to the first half of 2027, and the revenue moves into next year instead of disappearing. The contracts stay in place, and the company says none of the capacity is cancelled2
1
. One reported example is a 300-megawatt site in Vineland, New Jersey, where Microsoft is a major customer, held up by power delays1
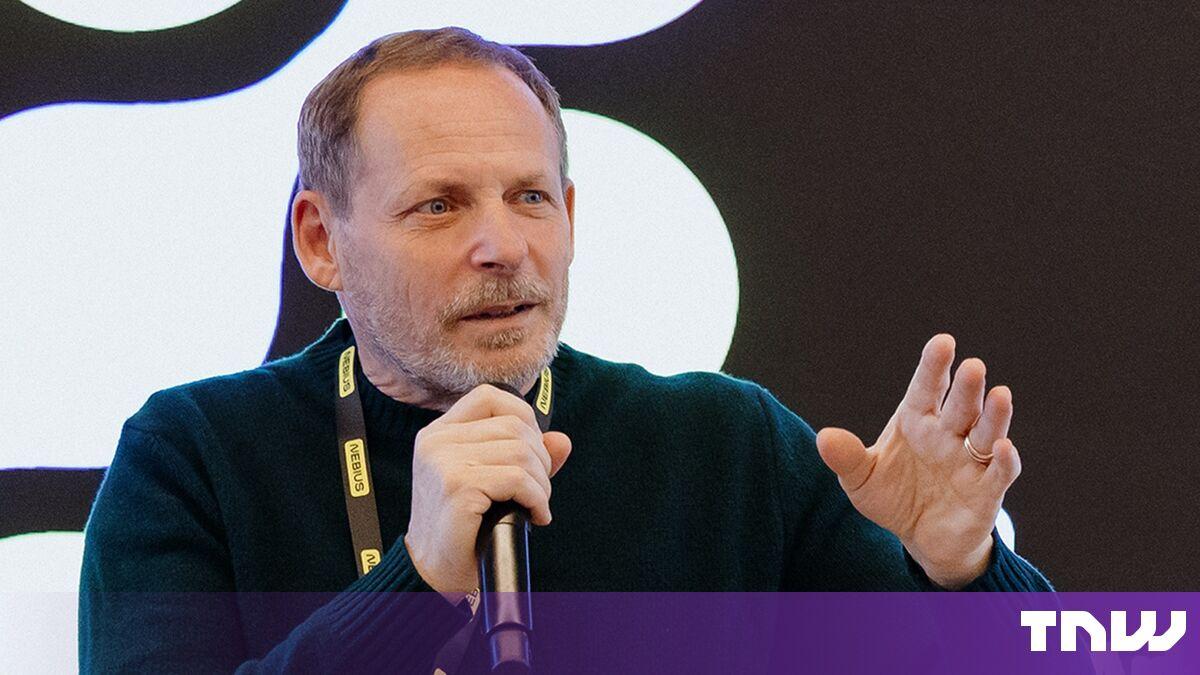
.Arkady Volozh, the founder and chief executive, framed the delays as an industry-wide condition that Nebius shares in. "Building at this scale is hard, and delays are part of our industry right now. We are not immune," he said
1
. All of the sites Nebius is building itself are on track or ahead of schedule, by its account, and most of the next gigawatt will sit on them1
. For 2027 the company guided to $12bn-$13bn in revenue. That is roughly in line with what analysts had projected, near $12.1bn2
1
.
Source: The Next Web
The quarter was fine
Nebius's net loss shrank to $37.5m, or 13 cents a share, from $119.6m a year earlier
2
1
. The cut landed despite the beat, so investors may read it as an execution problem rather than a demand one2
1
.Related Stories

The bill keeps climbing
Nebius raised this year's capital spending to about $27bn from an earlier $20bn-$25bn forecast, and plans $40bn-$45bn for 2027
1
. The 2027 plan sits well above the roughly $28.8bn analysts had expected for 20271
.Nebius's raise lands in a market already jumpy about how these upstart cloud operators pay for their buildouts. CoreWeave's rising borrowing costs were one trigger for that worry. The rival had eased some of it earlier in the week with its own revenue beat and a promise to rule out new unsecured debt
2
1
. Per one outlet, Nebius had already shed more than a third of its market value in October as investors questioned what the AI buildout costs1
.The company's answer is that customers will largely pay for it. Nebius expects prepayments and asset-backed financing against contracts with investment-grade customers, Microsoft and Meta among them, to cover 75%-85% of next year's spending. It also borrowed $3.5bn from Citi in October
2
1
. Volozh told investors the company can fund the buildout prudently with customer prepayments and a strong balance sheet. He credited the premium prices it charges and the infrastructure it builds itself2
. The CFO, Dado Alonso, said clients are already seeking capacity for 2028 and prices for 2027 are rising, so the company sees no risk on selling it1
."The demand for AI is real and substantial," Volozh said in the update. "Everything else, like building the capacity and financing it, is just a task."
1
References
Summarized by

Navi
Related Stories
Nebius Group Q2 Earnings Crush Expectations as AI Infrastructure Demand Drives 454% Revenue Surge
12 Aug 2026•Business and Economy

Nebius raises capex guidance to $25B as AI infrastructure demand surges through 2027
13 May 2026•Business and Economy
Nebius Auctions AI Compute Capacity at 20% Premium as Demand Outpaces Supply
09 Sept 2026•Business and Economy
Recent Highlights


Recent Highlights
Today's Top Stories






Don’t drown in AI news. We cut through the noise - filtering, ranking and summarizing the most important AI news, breakthroughs and research daily. Follow topics that matter to you and stay ahead.


