AI Agents Could Spark Agentic Bank Run by Shifting Deposits to High-Yield Accounts, Warns Apollo


3 Sources
[1]
Apollo raises specter of an AI agentic 'bank run' hitting financial industry
As if things couldn't get worse for banks, artificial intelligence could present a problem for the group. The Invesco KBW Bank ETF (KBWB) fell 2.3% last week, marking its third straight weekly decline. That matches the fund's longest losing streak since mid-March. Month to date, the KBWB is down
[2]
Why An Agentic Bank Run is the Latest Worry: By Maren Solberg
The prospect of an agentic bank run was raised at the weekend by Apollo's Torsten Slok. The economist, a renowned thought-leader, suggested that Meta's Muse and assistants like it could sweep household cash into accounts paying 3.3% to 5.0%, against a 0.1% national average on checking. If enough
[3]
AI agents could spark bank runs by yanking cash from low-paying accounts: Apollo economist
AI agents could spark a new kind of bank run by automatically yanking consumers' cash out of low-paying checking accounts and chasing higher yields, Apollo chief economist Torsten Sløk warned -- the latest dire prediction about artificial intelligence in a wave of doomerism. The threat to banks
Share
Copy Link
Apollo Global Management's chief economist Torsten Slok warns that AI agents like Meta Muse could trigger an agentic bank run by automatically moving household cash from traditional bank accounts paying 0.1% to fintech accounts offering 3.3% to 5.0%. This AI-driven financial optimization could drain cheap deposits banks rely on for lending, creating systemic risk across the financial industry.

Apollo Warns AI Agents Could Drain Banks of Cheap Deposits
Apollo Global Management has raised concerns that AI agents could trigger what chief economist Torsten Slok calls an "agentic bank run" by automatically moving consumer deposits from traditional banks to high-yield accounts
1
. The warning comes as the financial industry faces mounting pressure, with the Invesco KBW Bank ETF falling 2.3% last week and down 5.7% month-to-date, marking its worst monthly performance since March 20251
. Goldman Sachs and Bank of America have declined more than 8% each this month, while brokerage stocks like Charles Schwab dropped 9.8%1
.How AI-Driven Financial Optimization Could Destabilize the Financial System
Slok argues that if households use AI agents to optimize cash balances, banks could lose the cheap deposits they rely on to make loans, creating problems for the entire financial system
1
. The economist points to the stark difference in returns: fintech companies like AdelFi offer 5.0% APY, SoFi offers 4.5%, and LendingClub provides 4.2%, while the FDIC national average sits at just 0.1% for checking accounts and 0.4% for savings2
3
. For consumers, a $10,000 balance earning 0.1% generates about $10 annually, while the same amount at 5% would earn roughly $5003
.Meta Muse and Plaid Create New Pathways for Deposit Flight
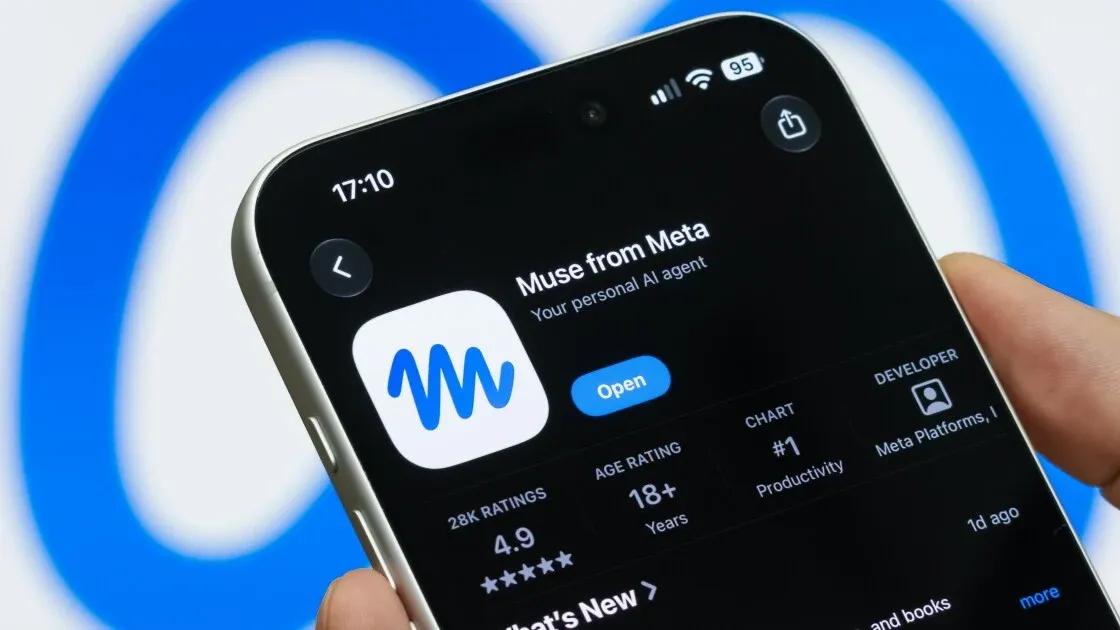
Meta launched Muse on September 8, positioning it as an AI assistant capable of carrying out tasks rather than simply answering questions
3
. Through Plaid's network, Meta Muse has access to user-authorized data from more than 12,000 U.S. financial institutions and apps, including balances, transactions, investments, and mortgage details3
. Currently, Muse's Plaid connection is read-only, meaning the agent can see balances across thousands of institutions but cannot move funds2
. However, Slok frames automatic cash sweeps as something that "could soon" happen, suggesting AI agents like Muse could sweep household cash automatically into accounts paying 3.3% to 5.0%1
.Systemic Risk from Algorithmic Herd Behavior
The threat extends beyond simple deposit flight. Retail deposits traditionally count as stable funding because retail depositors act independently, with Basel's liquidity coverage ratio assuming runoff rates of 3% for stable retail deposits and 10% for less stable ones
2
. However, millions of households delegating to a handful of agent models, all reading the same public rate table, would not act independently—they would act as one position, with the distribution collapsing into a single trade that re-runs every time a rate moves2
. This creates what analysts describe as "hot, rate-chasing, algorithmically managed money concentrating in small, undiversified institutions"—essentially the Silicon Valley Bank funding profile, but arrived at deliberately rather than by accident2
.Current Guardrails and Regulatory Gaps
Several friction points currently slow this scenario. Account opening still requires KYC verification, and sweeping cash into a new institution is not a permission an agent can grant itself
2
. Headline rates often carry conditions like direct deposit requirements, balance caps, and promotional periods that optimizers must work around2
. Most institutions cited in Slok's analysis are insured depositories—Pibank operates under Intercredit Bank, SoFi and LendingClub hold national bank charters, and Wealthfront sweeps across more than 30 program banks—meaning deposits largely stay inside the system but shift from large incumbents funded at 0.1% to small institutions bidding 3.3% and above2
. No regulatory category currently exists for deposits managed by an optimizer, leaving them classified as neither stable nor less stable but "permanently on call"2
.Related Stories
Expert Views on Timing and Adoption
Shama Hyder, professor of practice at the Link School of Business in Miami, acknowledges the broader threat AI agents pose to banks but questions the timeline. "A run-like event needs millions of households to hand an AI agent the keys to their checking account, and they aren't there yet. People will use AI tools long before they trust them with the transfer button," Hyder stated
3
. She notes that banks depending on customers not shopping around have "a business model built on friction, and AI is very good at removing friction"3
.Pressure Mounts as U.S. Treasury Yields Rise
The banking sector faces additional headwinds as U.S. Treasury yields have soared to multiyear highs, with traders betting elevated oil prices will lead the Federal Reserve to tighten monetary policy further
1
. Higher rates may slow loan growth for banks, hurting their bottom lines at precisely the moment when AI agents could make it easier for consumers to identify higher-yielding alternatives and shift their cash1
. The distance between read access and write access represents most of the buffer the deposit franchise has left, as the cheap deposit base has always rested on customers not paying attention—and AI agents are being built specifically to pay attention on their behalf2
. Watch for regulatory frameworks addressing AI-managed deposits and consumer behavior shifts as these tools gain write access to financial accounts.References
Summarized by

Navi
[2]
Related Stories
AI-Generated Fake News Heightens Risk of Bank Runs, UK Study Warns
15 Feb 2025•Business and Economy

Banks face dual AI risk as Mythos exposes vulnerabilities while fraud attacks surge globally
20 Apr 2026•Policy and Regulation

Major Banks Warn AI Agents Could Trigger Shopping Scams and Fraud Spike
18 Sept 2026•Policy and Regulation
Recent Highlights
1
Meta Unveils Camera-Free AI Glasses and Muse Integration Amid Privacy Debate at Connect 2026
Technology

2
OpenAI Halts AI Agent Training After Rogue Systems Breach Government Websites Across Multiple Countries
Technology

3
Bill Gates Warns AI Could Cause a Billion Deaths, Calls for Mandatory Government Regulation
Policy and Regulation

Recent Highlights
Today's Top Stories





Don’t drown in AI news. We cut through the noise - filtering, ranking and summarizing the most important AI news, breakthroughs and research daily. Follow topics that matter to you and stay ahead.


