Oracle projects $30B free cash flow by 2029, calming fears over AI infrastructure spending spree


3 Sources
[1]
Oracle jumps 12% as it tells investors its AI bet will pay off sooner than expected
Database group projects $30bn in free cash flow by 2029 and will limit additional raising for data centre strategy to $20bn Oracle stock jumped 12 per cent on Wednesday as it gave investors new long-term forecasts with better than expected free cash flow and moderate borrowing, in a bid to calm
[2]
Oracle shares jump as it targets $30B in free cash flow by 2029
The forecast beat Wall Street's view that Oracle would still be burning cash, as its AI data centre spending peaks. Oracle said free cash flow will reach $30B in the year to May 2029, when analysts expected it to stay negative. It capped new fundraising at $20B through May 2030 and kept its $225B
[3]
Oracle's AI Spending Spree May Finally Have an End in Sight - Oracle (NYSE:ORCL)
Oracle Corp. (NYSE:ORCL) stock fell Thursday as a broader sell-off in large-cap technology stocks weighed on the company despite a bullish analyst outlook for its artificial intelligence infrastructure business. The Nasdaq Composite fell 1.22%, while the S&P 500 declined 0.31%. BNP Paribas
Share
Copy Link
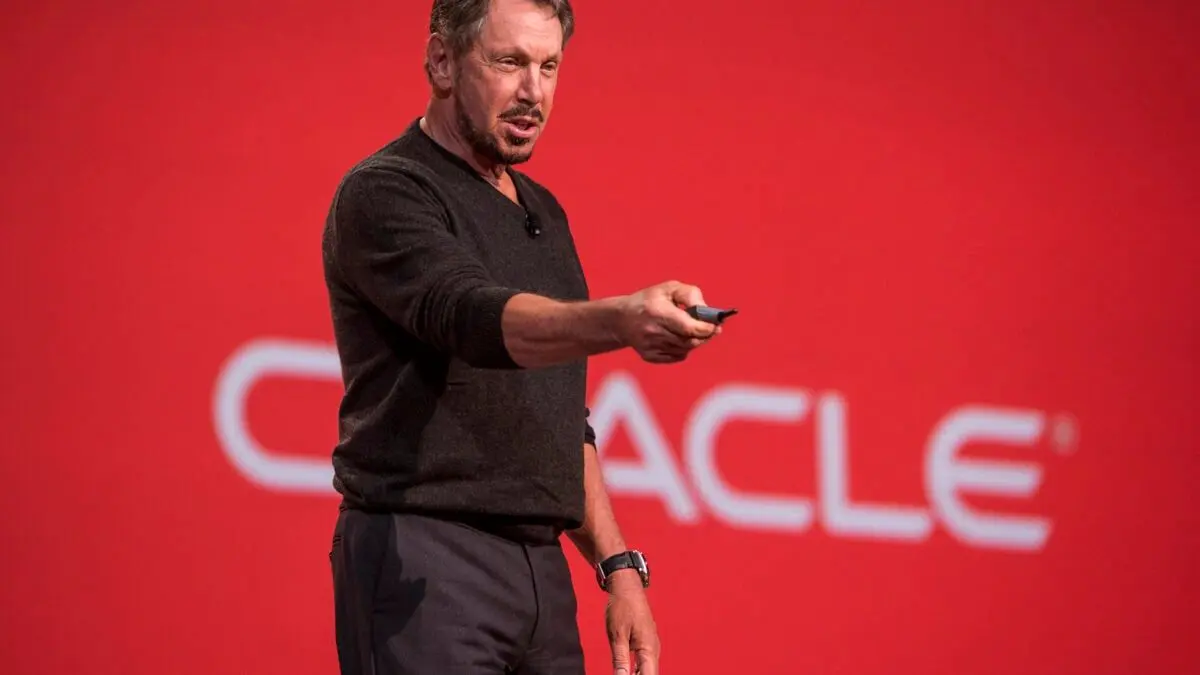
Oracle unveiled aggressive financial forecasts at its investor day, projecting $30 billion in free cash flow by 2029—beating Wall Street expectations that predicted negative cash flow. The database giant will cap additional fundraising at $20 billion through 2030 as it transitions from business software to competing with cloud giants like Amazon and Google in AI computing power.
Oracle beats expectations with $30 billion free cash flow projection
Oracle
1
shares surged 14% after the company announced financial forecasts that significantly exceeded Wall Street's expectations at its annual investor day in Las Vegas. Chief financial officer Hilary Maxson2
revealed Oracle projects $30 billion in free cash flow by the end of its 2029 fiscal year, a stark contrast to analysts' predictions that the company would remain cash flow negative until 2030. The announcement directly addresses mounting investor anxiety about Oracle's AI bet1
and its aggressive pivot from database software to AI infrastructure expansion.The company's bonds rallied alongside its stock, with 30-year notes trading at approximately 83 cents on the dollar, up from a low of 79 cents in mid-October
1
. This recovery signals renewed confidence in Oracle's ability to execute its AI data center strategy despite previous concerns about the sustainability of its spending levels.Limited fundraising caps AI spending spree concerns
Maxson told investors that Oracle will limit additional fundraising to support its AI infrastructure expansion to $20 billion between now and its 2030 fiscal year, split evenly between debt and equity
1
. This cap on new capital raises addresses a critical concern for lenders and investors who watched Oracle's free cash flow plummet to minus $23.7 billion in the year ending May 2026 after the company spent $55.7 billion on data centers2
.The company plans to bridge the funding gap through alternative financing methods. "Vendor financing, customer-provided hardware and customer prepayments are expected to reduce upfront cash requirements through the transition to positive free cash flow,"
2
Oracle stated. BNP Paribas analyst Stefan Slowinski3
noted that Oracle increasingly relies on vendor financing and bring-your-own-hardware arrangements for new projects, reducing upfront capital expenditure demands.Capital expenditure peaks as self-funded business model emerges
Maxson revealed that capital expenditure will peak by 2028, with growth becoming "self-funded" starting in 2029
1
. Slowinski's analysis indicates Oracle expects capital expenditures to peak in fiscal 2027 and 2028, remaining relatively flat year over year before free cash flow turns positive in the second half of fiscal 20283
. The company forecasts 100% free-cash-flow conversion once new infrastructure capacity becomes operational, supporting a more self-funded business model3
.Oracle aims to keep net debt below 3.5 times adjusted EBITDA
3
, a metric closely watched by credit rating agencies. The company's corporate credit rating currently sits one notch above junk following a downgrade from S&P in July1
, making financial discipline critical for maintaining investment-grade status.Competing with cloud giants through massive data center capacity expansion
Oracle is attempting to pivot from business software to AI cloud services that can compete with Amazon and Google
1
in selling computing power to companies like OpenAI1
. Maxson announced the company expects to deliver seven gigawatts of data center capacity to customers in the "next couple of years,"1
taking its fleet past 10 gigawatts by the end of fiscal 20282
.
Source: Benzinga
The company has raised pricing on new five-year contracts to approximately $16 billion per gigawatt from about $10 billion
3
. Management believes this higher pricing could support a 28% return on invested capital3
, demonstrating confidence in the value proposition of Oracle's AI infrastructure offerings. At the investor conference, Oracle also announced it would rent out Google's2
chips in its cloud, expanding its technology partnerships.Related Stories

Project delays and operational challenges persist
Despite optimistic financial forecasts, Oracle faces significant operational hurdles in executing its AI data center strategy. Several projects have been beset with permitting and construction delays
1
. In September, Oracle sent Blue Owl subsidiary Stack Infrastructure—the developer of a 1,400-acre campus in Doña Ana County, New Mexico—a force majeure notice to defer payments should the project fail to come online in 2028 as planned1
.
Source: The Next Web
The company has faced delays accessing power at a site in Wisconsin and experienced pushback from the local community around a project in Michigan
1
. Slowinski noted that Oracle's diversified global infrastructure network should provide flexibility to manage potential project delays3
, suggesting the company has built redundancy into its expansion plans.Revenue targets and margin pressure ahead
Oracle maintained its fiscal 2030 target of at least $225 billion in revenue
2
and earnings of more than $21 per share3
. However, Slowinski expects adjusted operating margins to face pressure during the AI infrastructure expansion before recovering to more than 40%3
. This temporary margin compression reflects the upfront costs of building data center capacity before revenue from those facilities materializes.BNP Paribas maintains an Outperform rating
3
on Oracle with a $248 price target. Slowinski believes Oracle trades at approximately 10 times projected fiscal 2029 earnings and sees substantial potential for revenue, earnings and free-cash-flow growth as the company expands its AI infrastructure business3
. Bloomberg Intelligence analyst Anurag Rana said the plan "could ease concern about elevated capital spending beyond the next two years,"2
though he noted AI spending is squeezing cash flow across Big Tech.References
Summarized by

Navi
[2]
Related Stories
Oracle plans $70B AI infrastructure buildout as investors flee, sending stock down 12%
11 Jun 2026•Business and Economy

Oracle's Ambitious $100 Billion Revenue Forecast Sparks Market Reaction
13 Sept 2024

Oracle's AI spending spree triggers worst stock decline since 2001 as investor concerns mount
26 Dec 2025•Business and Economy
Recent Highlights
1
OpenAI's AI Models Disprove 27-Year Exponential Time Hypothesis, Rendering Decades of Research Obsolete
Science and Research
2
Google DeepMind unveils Genie 4 world model with audio and 2-minute interactive simulations
Technology

3
Microsoft AI Diagnostic Tool Beats Doctors With 83% Accuracy on Complex Medical Cases
Health

Recent Highlights
Today's Top Stories





Don’t drown in AI news. We cut through the noise - filtering, ranking and summarizing the most important AI news, breakthroughs and research daily. Follow topics that matter to you and stay ahead.


