Western Digital Reports 28% Price Growth as AI Storage Demand Extends Visibility to 2030


2 Sources
[1]
Western Digital Expects Price Growth to Cool and Storage Demand to Hold - Western Digital (NASDAQ:WDC)
Western Digital Warns HDD Price Growth Will Eventually Slow -- But AI, Inference and Robotics Are Keeping Demand Strong Western Digital Corp. (NASDAQ:WDC) expects price growth for its hard drives to cool eventually, but sees demand for storage staying strong, with artificial intelligence,
[2]
Western Digital 1Q Profit Grows on Data Storage Demand, Higher Pricing -- Update
Western Digital's profit and revenue grew in the fiscal first quarter, as the company capitalizes on growing data-storage demand tied to the build out of artificial-intelligence infrastructure. Demand for Western Digital's hard disk drives remains strong, Chief Executive Irving Tan told analysts
Share
Copy Link
Western Digital posted first-quarter earnings of $4.64 per share, beating estimates of $4.06, with revenue at $4.38 billion versus $4.14 billion expected. CEO Irving Tan confirmed visibility through 2030-2031 across top customers, driven by AI infrastructure expansion, inference workloads, and robotics. Despite a 28% rise in blended average selling price per terabyte, CFO Kris Sennesael warned hard drive price growth will eventually cool.
Western Digital Beats Q1 Estimates With Strong AI-Driven Performance
Western Digital delivered first-quarter earnings of $4.64 per share, surpassing Wall Street's estimate of $4.06, while revenue reached $4.38 billion against expectations of $4.14 billion
1
2
. The company's profit grew to $1.78 billion, or $4.63 a share, compared with $1.15 billion, or $3.07 a share, a year earlier2
. For the second quarter, Western Digital expects adjusted earnings between $5.60 and $6.00 per share, significantly above the $4.74 analyst estimate, with revenue projected at $5 billion to $5.2 billion versus the $4.52 billion estimate1
. The blended average selling price per terabyte of storage rose 28% during the first quarter, reflecting the company's ability to command premium pricing amid tight supply conditions1
2
.AI Storage Demand Provides Visibility Through 2030
CEO Irving Tan revealed "good visibility up to 2030, 2031" across Western Digital's top seven customers, with the demand signal "actually increasing" quarter after quarter
1
. Tan told analysts that data storage demand tied to AI infrastructure expansion remains strong and is increasingly coming from customers outside the company's core base, such as neoclouds and AI frontier labs2
. The CEO identified four key growth drivers: cloud, model training, AI inference workloads, and agentic AI, alongside physical AI including robotics, which he described as "becoming a key area"1
. This extended visibility underscores how AI infrastructure buildout is reshaping the data storage landscape, creating sustained demand from neoclouds and specialized AI workloads that require massive storage capacity.Hard Drive Price Growth Expected to Cool Despite Strong Fundamentals
While Western Digital enjoys robust pricing power today, CFO Kris Sennesael cautioned that hard drive price growth will eventually slow down. "I would assume eventually that is going to slow down a little bit," Sennesael told analysts during the earnings call
1
. However, he still sees "further room" for price per terabyte growth over the next three to four quarters as long-term agreements expire and are repriced, and drives sold outside contracts continue commanding strong prices1
. Concerns about future supply emerged after reports that Toshiba plans to nearly double HDD production capacity by fiscal 2027 compared with fiscal 2025 on a storage-capacity basis1
. When pressed on rival capacity additions, Irving Tan maintained he sees no change at a high level in the industry's "long-term fundamentals" and emphasized that Western Digital is "committed to not investing in any incremental unit capacity"1
.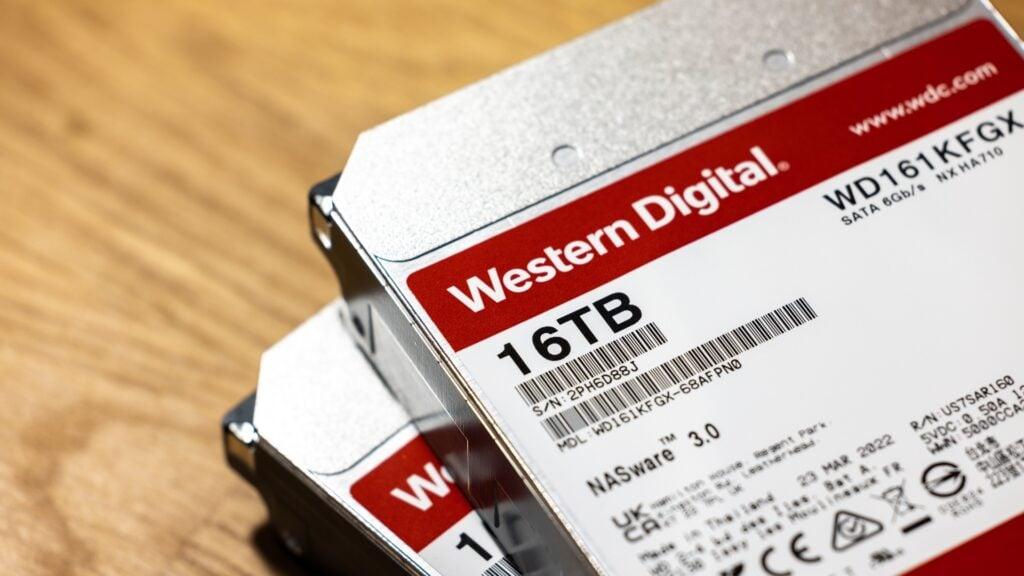
Source: Benzinga
Related Stories

Market Reaction and Strategic Positioning
Western Digital shares closed 6.43% lower on Thursday at $354.19 and fell an additional 6.54% to $331.01 in extended trading, despite the strong earnings beat
1
. Investors broadly rotated out of AI-connected stocks on Thursday, fueled in part by capital spending disclosures from Meta Platforms2
. Over the past month, the stock declined 23.76% but remains up 105.6% year-to-date1
. Western Digital also lifted its quarterly dividend by 17% to 17.5 cents a share, payable on December 17 to shareholders of record as of December 42
. The post-earnings analysis suggests investors are weighing valuations, future supply growth from competitors, and the financing burden behind AI infrastructure buildout against Western Digital's strong demand fundamentals and extended visibility through 2030.References
Summarized by

Navi
[1]
Related Stories
Western Digital Shares Tumble as Q4 Revenue Misses and Outlook Disappoints
01 Aug 2024

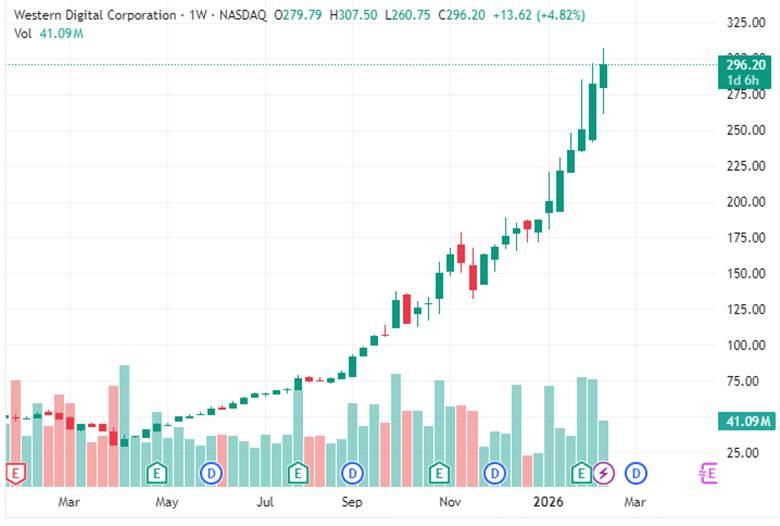
Western Digital's 970% surge reveals AI's hidden storage crisis as hyperscalers lock in supply
12 Feb 2026•Technology
AI Boom Triggers Storage Crisis: HDD and SSD Prices Surge Amid Supply Shortages
16 Sept 2025•Technology
Recent Highlights


Recent Highlights
Today's Top Stories


Don’t drown in AI news. We cut through the noise - filtering, ranking and summarizing the most important AI news, breakthroughs and research daily. Follow topics that matter to you and stay ahead.


